10:33W35
An Exclusion Is Not Your Carrier's Opinion. Five Checks Before You Accept One
Most exclusions in a homeowners policy were drafted by an advisory organization and reviewed by a state regulator, and that changes how you read the denial letter.
Money4 min
When a claim is denied, the letter usually quotes a paragraph and stops there, as though the paragraph arrived from nowhere and settles the matter by its own authority. It did not arrive from nowhere. Most of the exclusions in a standard homeowners policy were drafted by an insurance advisory organization, adopted with edits by the carrier, and then filed with and reviewed by the insurance department of the state where the policy was sold. Three parties touched the sentence before you did, and the one most people overlook is the regulator.
Check who drafted the wording and who approved it
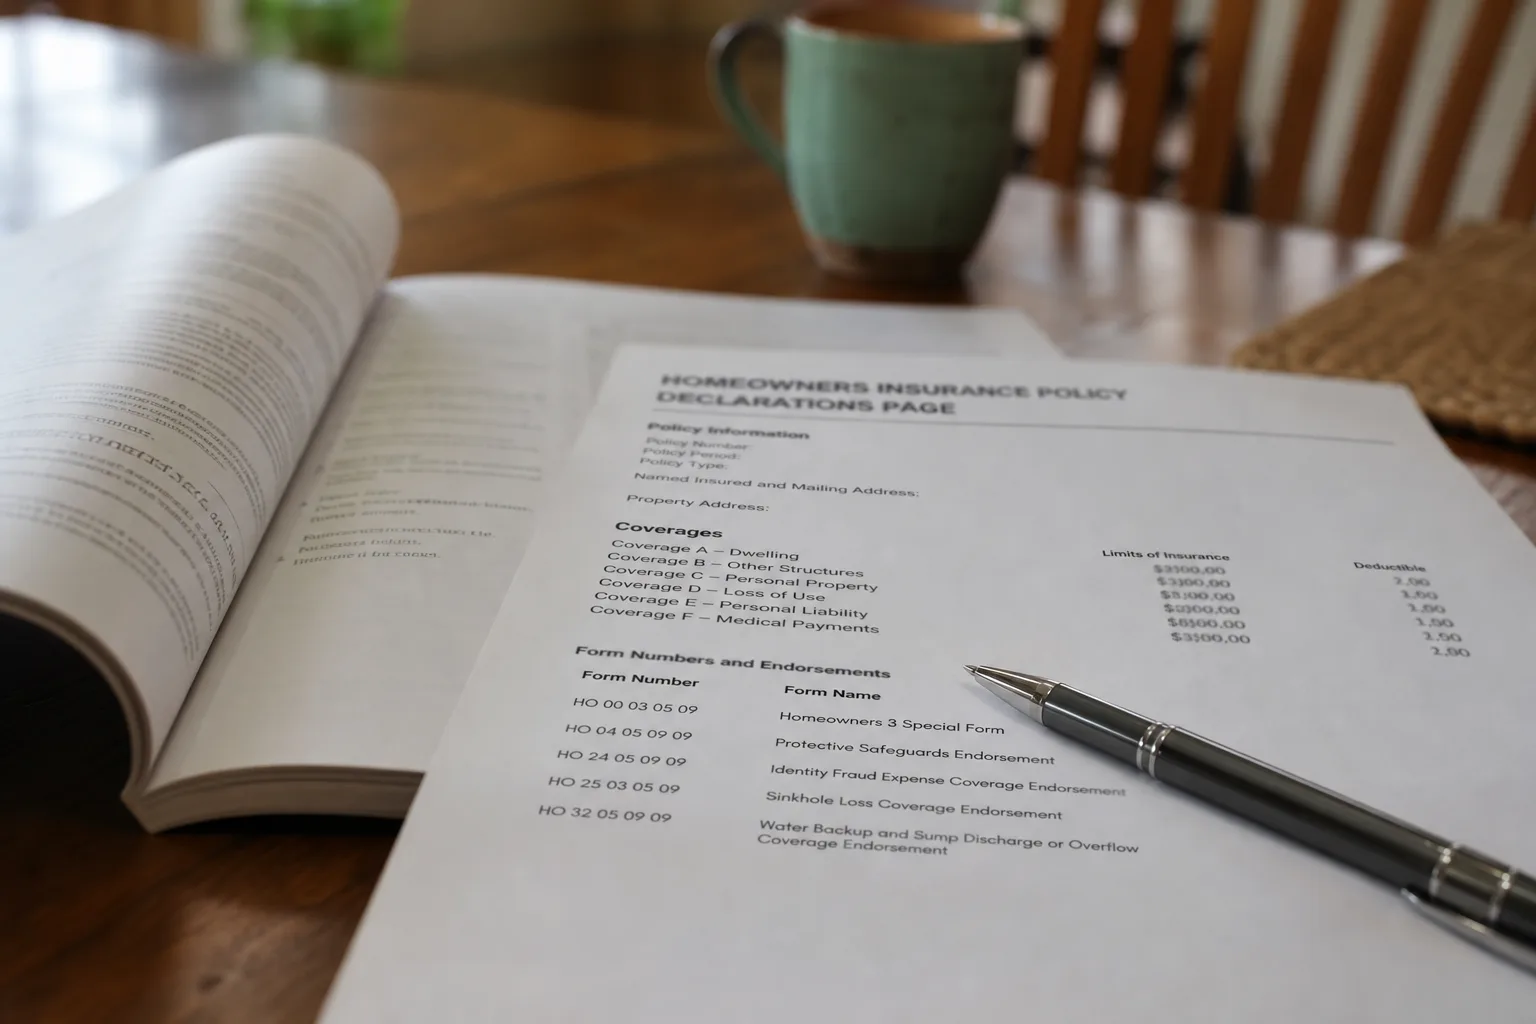
Carriers rarely write policy language from scratch. They license standardized forms from an advisory organization, modify them where they want to compete or retreat, and file the result with each state's insurance department for review before it can be sold. That review is not a rubber stamp in every state, and it is the reason the same named-peril language shows up in policies from companies that agree on nothing else. The practical consequence is that your form has a number and an edition date, both printed on the declarations page, and that number identifies a document your state has on file.
This matters when an adjuster paraphrases. A paraphrase can drift, and the filed form is the version that governs. Asking for the complete policy, not the summary, is a routine request that adjusters handle daily without objection, and it costs nothing.
Check whether the exclusion exists because another market sells the coverage
Some exclusions are not judgments about your risk at all. They are boundary markers between two products. Flood is the clearest case: the standard homeowners form excludes surface water because flood coverage moved into a separate federal program decades ago, and the Federal Emergency Management Agency is responsible for administering that program and the private carriers that write policies under it. Earthquake works similarly in most states, sold as its own policy or its own endorsement with its own deductible structure. Read those exclusions as directions rather than refusals, because the coverage exists and someone is licensed to sell it to you.
The distinction changes what you do next. An exclusion that reflects an underwriting decision invites an argument about facts. An exclusion that marks a market boundary invites a phone call to a different desk, and that call is usually the faster route to being covered next time.
Check the exception sitting inside the exclusion
Exclusions in property forms are frequently written as an exclusion with a carve-back, and the carve-back is where a great many claims are actually paid. The classic structure excludes a cause of loss but then restores coverage for an ensuing loss that the excluded cause sets off. Faulty workmanship is commonly excluded; the water damage that follows a badly soldered joint may not be. Wear and tear is excluded; the sudden collapse it eventually produces can land differently depending on the wording and the state.
These sentences are dense on purpose, and the anti-concurrent causation language that often precedes them changes how two overlapping causes are treated. Reading the whole clause, including the paragraph after the one quoted in the denial, is the single highest-value ten minutes available to a policyholder.
Check what happens when code requires a better replacement than what burned
Standard forms exclude the extra cost of complying with an ordinance or law, which sounds abstract until a furnace, a water heater, or a roof assembly has to be replaced to a current energy code rather than the one in force when the house was built. The greener replacement is often the only legal replacement, and the efficiency gain is real, but the policy as written pays to restore what was there. Ordinance or law coverage is the endorsement that closes that gap, sold in percentage tiers of the dwelling limit, and it is inexpensive relative to what a code-driven upgrade costs out of pocket.
Homeowners who have already done efficiency work have a second version of this problem, since a heat pump or a sealed building envelope may be worth more than the equipment it replaced. The fix is a conversation with the agent about limits and endorsements, held before a loss rather than after.
Check whether the exclusion can be bought back on your policy
A surprising share of exclusions are negotiable in the ordinary retail sense: the carrier will delete or narrow them for additional premium, through a named endorsement listed on the declarations page. Water backup from sewers and drains, service line failure, refrigerated property spoilage, and business property used in a home office all follow that pattern. Whether a given buy-back is available depends on the carrier, the state filing, and the condition of the house. Ask the agent to price the endorsement and to name the form number, then confirm the number appears on the next renewal declarations before assuming it took effect.
The declarations page is a table of contents to a document three parties built, and the form numbers printed on it are the fastest way to find out which version of the sentence applies to you. Pull it out before the deposit on repairs goes down, not after.