10:19W35
Every Exclusion Has a Buyback Price, and Your State Decides What It Is
Exclusions are priced decisions, not legal afterthoughts, and what it costs to remove one depends heavily on the state and the town you are buying in.
Money5 min
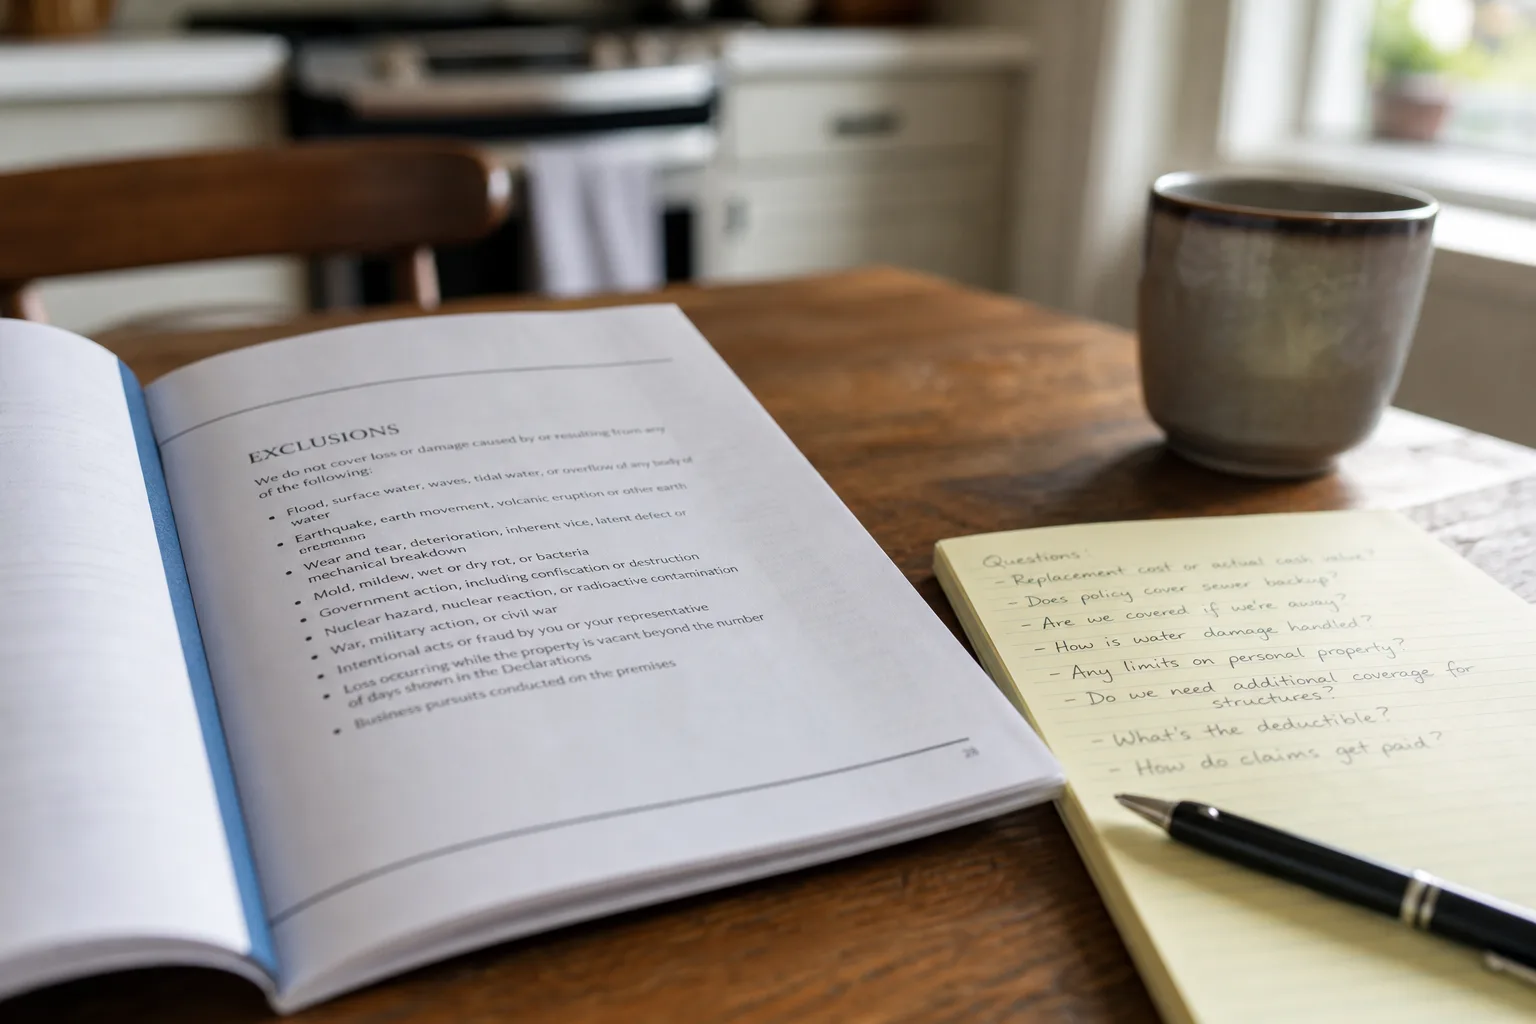
The exclusions page is the part of a homeowners policy that most people meet twice: once when it arrives in the mail and goes into a drawer, and once when an adjuster reads it back to them. That is a shame, because it is the most honest page in the document. The declarations tell you what you bought. The exclusions tell you what the carrier decided it could not sell you at the price you were willing to pay, and, in most cases, what it would charge to sell you some of it after all. Read that way, an exclusion is not a trap. It is a menu item with the price hidden one page over.
An exclusion is a pricing decision that arrived in legal clothing
Underwriters exclude perils for a few recognizable reasons, and none of them is malice. Some losses are so correlated that a single event hits every policyholder in a book at once, which is the flood and earthquake problem, and correlated risk destroys the arithmetic that makes pooling work. Some losses are close to certain over a long enough horizon, like wear, rot, and settling, and a policy that pays for the inevitable is a savings account with a worse return. Some losses sit in the gap between an accident and a maintenance failure, which is where seepage and repeated leakage live. The clause exists because the actuary could not price the exposure inside a standard premium, not because someone in a legal department got clever after hours.
That distinction matters for what you do next. A peril excluded because it is uninsurable at any retail price, at least outside a government program, has to be solved somewhere else. A peril excluded because it is expensive, volatile, or unevenly distributed usually has a corresponding endorsement, and the endorsement has a number. Water backup through sewers and drains is the everyday example, and so are ordinance or law coverage, service line coverage, and, in many states, a separate buydown of a percentage wind deductible. The exclusion and the endorsement were written by the same people. One is the default, the other is the upsell, and the difference between them is your annual premium plus a judgment about how much of the tail you want to keep.
What buying one back actually costs, and what moves the number
I am not going to invent figures, because the honest answer is that the spread is enormous and the drivers are legible. What you can predict is the shape. Endorsements that restore a narrow, capped peril, water backup at a modest limit or service line coverage, tend to be the cheapest thing on the page, often a rounding error against the base premium, and they are cheap because the carrier caps its own exposure in the same sentence that grants the coverage. Ordinance or law is priced as a percentage of your dwelling limit, so it scales with the house rather than with the risk. Wind deductible buydowns and standalone earthquake or flood are a different order of magnitude entirely, because there the carrier is buying back the correlated exposure it deliberately shed.
Within any one of those, the levers are the ones underwriters actually look at: the limit you choose, the deductible you accept against it, the age and material of the roof, the construction type, the distance to a coast or a brush line, the loss history on the property and in your own name, and increasingly the mitigation you can document. That last one is where a retrofit stops being a slogan and starts being a line item. A backwater valve on the sewer lateral, hurricane straps and a nailing pattern recorded on an inspection form, defensible space cleared and photographed, a water shutoff device with a monitoring feed. These change the price of the buyback in a way that a general claim of efficiency or resilience never does, because the rating plan has a field for them and no field for good intentions.
The same clause does not behave the same way across a state line
Insurance in this country is regulated state by state, and policy forms and rates are filed with and approved by each state's department of insurance, which is why two neighbors on opposite sides of a border can hold documents with matching language and materially different outcomes. Anti-concurrent causation, the provision that says a loss caused partly by an excluded peril is excluded even if a covered peril also contributed, is enforced as written in many states and read down sharply in others. Some states require matching of undamaged materials so a patched roof slope does not become your problem; others leave it to the adjuster. Cosmetic hail damage exclusions are common through the hail belt and rare elsewhere. Sinkhole coverage is a statutory conversation in Florida and a curiosity almost everywhere else.
The regional pattern also decides which exclusions have a functioning market behind them. Percentage wind and named storm deductibles are standard along the Gulf and Atlantic coasts and unusual inland, and the buydown market follows the exposure. Wildfire has reshaped the California market to the point that the exclusion question is often really a question about the state's insurer of last resort and what a difference-in-conditions policy costs on top of it. Flood is excluded almost universally in homeowners forms and handled instead through the National Flood Insurance Program, which the Federal Emergency Management Agency is responsible for, alongside a private flood market that has grown around it and that prices some properties better than the program does.
The local layer that quietly sets the size of the gap
Below the state, the town does something more specific: it decides how expensive it will be to rebuild legally. Ordinance or law coverage exists because your policy pays to restore what burned, while your building department requires what the current code demands, and the distance between those two is set by which code cycle your jurisdiction adopted, whether it added local amendments, and how aggressively it applies the fifty percent substantial improvement threshold. A coastal town enforcing a current flood ordinance may require elevation on a rebuild that the old house never had. A city with combined sewers may leave the lateral, and the backup, entirely with the homeowner. None of that appears in the exclusion. All of it determines what the exclusion costs you.
So the useful exercise, before renewal rather than after a loss, is to take the exclusions page to your agent and ask for a quoted price on each item that has an endorsement, then ask which of them your zip code, your roof, and your documented mitigation actually move. You will find that two or three cost very little and close the gaps that adjusters see most often, and that one or two are expensive for reasons that are specific to where you live and worth understanding before you decline them.
The page is short. Priced out loud, it turns from a list of refusals into a set of choices you are making anyway, whether or not you read them.