15:06W32
Hail Claim or Notice Only? The File One Homeowner Built Before Deciding
A hailstorm, a street full of roofing signs, and one homeowner who documented everything for two weeks before deciding whether to file at all.
Money5 min
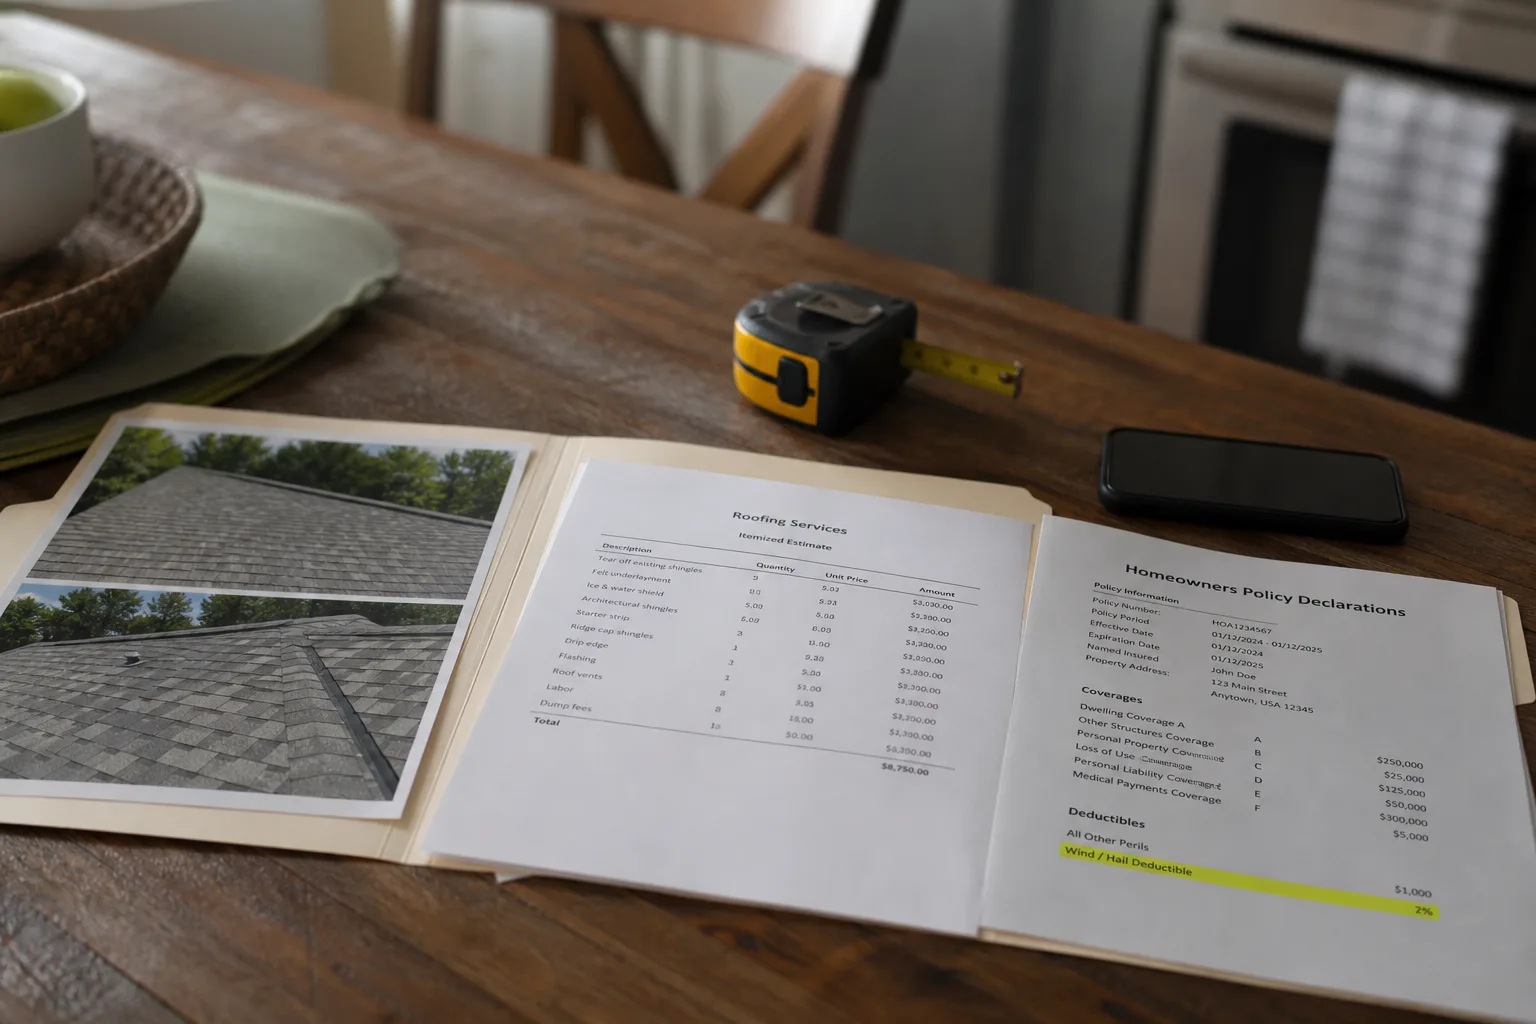
The decision that shaped this case was made about eleven days before anything was reported to the carrier, and it was made with a folder rather than a phone call. A hailstorm crossed a county where percentage wind and hail deductibles are standard, and within seventy-two hours the street had roofing signs on half its lawns. The homeowner, whose roof was in its eleventh year of an architectural asphalt product, did not call her agent that week. She called a roofer she had used before, paid for an inspection, and started writing things down.
A storm, a street full of signs, and a decision held open
The pressure in a hail event runs one direction: file now, file fast, let the crew handle it. Contractors canvassing after a storm are not doing anything improper by knocking, and some of them are excellent, but their interest is in a signed contract and yours is in a roof and a renewal. What this homeowner understood, and what the trade rarely spells out for a first-time claimant, is that the report to the carrier is the irreversible step. Estimates, inspections, photographs and a written scope are all reversible. She sequenced accordingly.
The inspection produced a specific finding rather than a conclusion. Bruising was concentrated on the west and south slopes, with granule loss visible at the impact points and two soft spots on the ridge; the north slope was largely intact. Her roofer marked test squares, chalked the hits, photographed each one against a tape, and wrote a scope covering two slopes plus ridge and vents. He also told her, without being asked, that a two-slope repair on an eleven-year-old shingle would leave a visible color difference, and that whether the carrier would pay for the other two slopes depended on a matching provision she had never read.
The file she built in the first two weeks
The file was ordinary and it was the whole advantage. Photographs with timestamps, taken from the ground and from the ladder, including wide shots that establish which slope is which. A copy of the roofer's written scope, itemized by slope, with quantities. A one-page log recording every call: date, who she spoke to, what was said, what was promised next. Screenshots of the storm date from the National Weather Service record for her county, saved as a PDF. Her declarations page, printed, with the deductible figure and the wind and hail endorsement highlighted.
Two documents did more work than the rest. The first was her policy's loss settlement language, which paid replacement cost only after repairs were completed and documented, holding back depreciation until she submitted invoices. The second was the deductible: written as a percentage of dwelling coverage rather than a flat dollar amount, which on a house insured near its replacement value produced a number in the mid four figures. She wrote both on the front of the folder. A repair that lands anywhere near that figure is not a claim in any meaningful sense, and knowing it before the call changed what the call was about.
She also asked her roofer for the scope in the estimating format most carriers use, so the two documents could be compared line by line rather than argued about in general terms. Adjusters and contractors both work in that software, and a scope written in it is a conversation between professionals rather than a homeowner's complaint. When the field adjuster later came out, the disagreement was narrow: three squares and the ridge cap, not the existence of damage. Narrow disagreements settle.
What the loss history record actually shows
The part of this that homeowners consistently misunderstand is where their claims history lives. It is not held only by the carrier. It sits in a consumer reporting database that insurers query at quoting and at renewal, and because it is a consumer report, it falls under the federal rules the Federal Trade Commission is responsible for administering. You can request your own copy, you can see what has been recorded against the property, and you can dispute an entry that is wrong. She requested hers before she filed, which took a few days and cost nothing.
What she found was one entry from a prior owner, coded as a weather-related loss, closed without payment. That mattered for a practical reason: underwriters read frequency as a pattern, and a property carrying several coded entries is treated differently from one carrying a single storm loss, even where the dollar amounts are modest. Whether a call that produces no payment gets coded at all varies by carrier and by state, and several states limit what an insurer may do with a weather-related loss in a declared event. Her state insurance department publishes that guidance, and reading it took twenty minutes.
So she made the call as a report of a storm loss with a scope already in hand, not an open-ended question about whether something might be covered. The distinction is not a trick. It shortens the file, gives the adjuster something to inspect against, and keeps the conversation on the roof rather than on the house generally, which is how unrelated observations end up in a claim file and, later, in an underwriting note.
The shingle upgrade, and the part of the label doing the work
The full replacement was approved once matching was resolved, and that opened a question worth more than the claim. Impact-rated shingles are tested by dropping steel balls of graduated size onto samples, and the top classification under that standard is what carriers mean by Class 4. Many carriers in hail states discount premium for it. The discount is real and it is also modest, and the honest math is that the upgrade pays back through the deductible you do not spend on the next storm rather than through the line item on the declarations page.
She priced it as an out-of-pocket difference against the approved scope, since the policy pays for like kind and quality and not for a better roof. The upgrade added a manageable sum on a job that was otherwise covered, and her carrier confirmed the discount in writing before the order went in, which is the step people skip. The other labels on the sample board did less. A cool-roof reflectivity rating on a dark architectural shingle in a mixed climate changes attic temperatures at the margin; on this house, with a vented attic and adequate insulation, it was the label rather than the physics doing most of the talking. She bought the impact rating and passed on the rest.
The renewal, and what carried over
Renewal arrived with a premium increase, and the increase was not really about her. Rates in the county moved after the storm, and every quote she pulled reflected it. What she could verify, because she had the loss history report, was that her file showed one weather-related claim, paid, with the depreciation released after she submitted the completed invoices. No open items, no unresolved correspondence, no second entry from an inquiry that went nowhere. Her agent added the impact-resistant credit at renewal, and the roof certification the manufacturer issued went into the same folder.
The folder is the transferable part. A dated log, a scope in the format the trade actually uses, the declarations page with the deductible read rather than assumed, and a copy of your own loss history pulled before you pick up the phone. None of it requires a lawyer or a public adjuster on a single-peril roof loss. It requires deciding that the report is the last step in the sequence instead of the first, which is the one thing you cannot go back and change.