08:01W32
Enrollment Deposit, Auto-Billed Books, a Housing Contract. Where the Non Fee Money Actually Goes
Beyond tuition, the money that moves first is tied to deadlines: deposits, automatic course material billing, and housing terms that changed in the last few years.
Schools4 min
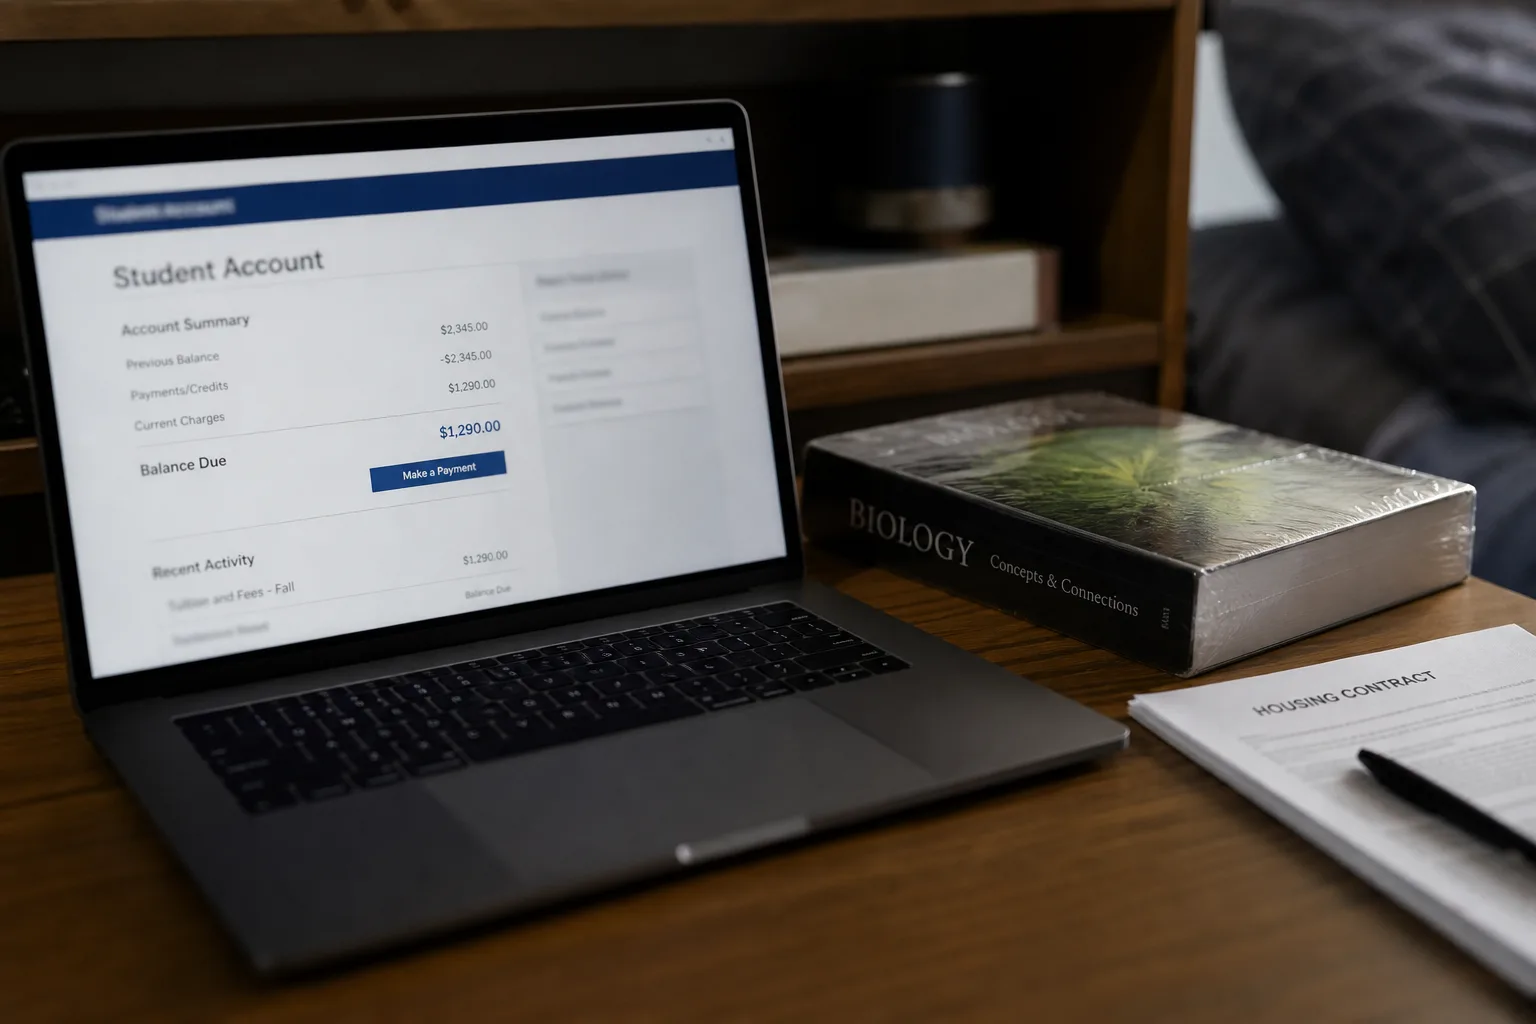
Tuition is the number families argue about, and it is rarely the number that moves first. Before a single class meets, a household has usually committed several thousand dollars through instruments that behave nothing like tuition: an enrollment deposit that confirms a seat, a housing deposit that reserves a bed, a meal plan that starts billing on a fixed date, and a course materials charge that appears on the student account automatically unless somebody declines it in writing. Each has its own deadline, its own refund rule, and its own answer to the question of what happens when the student changes course.
The deposit is a decision, not a placeholder
An enrollment deposit is small relative to a year of study and almost always nonrefundable after the stated date, which is the point of it: the school is buying certainty about class size, and the family is buying a seat. What shifted recently is the calendar. Federal financial aid application delays in the last two cycles pushed award letters later, and many institutions responded by moving deposit deadlines back, extending them in waves, or accepting late deposits without penalty. The extensions were real but uneven, campus by campus, which means the operative date is the one in the student's portal rather than the one in the general advice.
Housing deposits run on a separate clock
The housing deposit is frequently larger than the enrollment deposit, and it is governed by a contract that most families sign electronically without reading the release terms. Two things drive the cost. The first is timing, because assignment priority is often keyed to deposit date, and the better inventory is claimed early by people willing to commit before their aid package is final. The second is the term of the agreement. Many campuses now write housing for the full academic year rather than semester by semester, so a student who leaves in December may owe part of the spring, subject to a release process with a documented reason and a review committee.
Course materials moved onto the tuition bill, and the opt-out has a deadline
The most consequential change in non-fee spending over the past several years is not a price increase; it is a billing method. Under what schools variously call inclusive access, day-one access, or equitable access, digital textbooks and courseware are charged to the student account, either per credit hour or per course, and delivered through the learning platform on the first day of the term. The Department of Education oversees the federal aid rules that permit this arrangement, and those rules require a genuine opt-out. The catch is practical rather than legal: the opt-out window is short, often closing within the first two weeks, and it lives in an email that competes with fifty others.
Whether the program saves money depends on the student's actual course load. For a schedule heavy in sciences and business, where new-edition access codes are unavoidable, the bundled rate usually beats retail. For a schedule of seminars with paperbacks that circulate used for a few dollars, the flat per-credit charge can cost more than buying everything outright. The comparison is worth an hour in August, and it is the rare education expense where a family can reduce the bill by acting rather than by qualifying for something.
What withdrawal actually keeps and what it returns
The refund question is where the pieces separate. Tuition typically follows a published proration schedule that shrinks fast, often to zero within the first month. Federal aid follows a separate calculation entirely, based on the percentage of the term completed, with the school required to return unearned funds and the student sometimes left owing a balance created by that return. Housing follows the contract. Meal plans follow their own daily or weekly proration. Auto-billed course materials are usually credited if the student drops within the add-drop period and not credited afterward, because access was already delivered.
The result is that leaving in week two and leaving in week eight are financially different events by an order of magnitude, and the difference has almost nothing to do with how much instruction was received. Anyone weighing a withdrawal should ask the bursar for a written estimate of the final balance under two specific dates before deciding, because the answer is calculable in advance and frequently changes the timing of the decision.
The costs that only appear once you are enrolled
Program-specific spending is the quiet driver: clinical placement fees, background checks and immunization records for health programs, studio and lab kits, a laptop meeting a department specification, licensure exam registrations, and transportation to placements that may sit thirty miles from campus. Schools publish a cost of attendance figure that includes estimates for these, and that figure carries real weight because it sets the ceiling on borrowing. Reading it closely, line by line, tells a family what the institution already expects them to spend.
Ask for the three dates that matter, the deposit deadline, the materials opt-out close, and the last day for a full housing release, and write them somewhere a person will look. Most of the money that gets forfeited in education is forfeited by a calendar, not by a choice.